
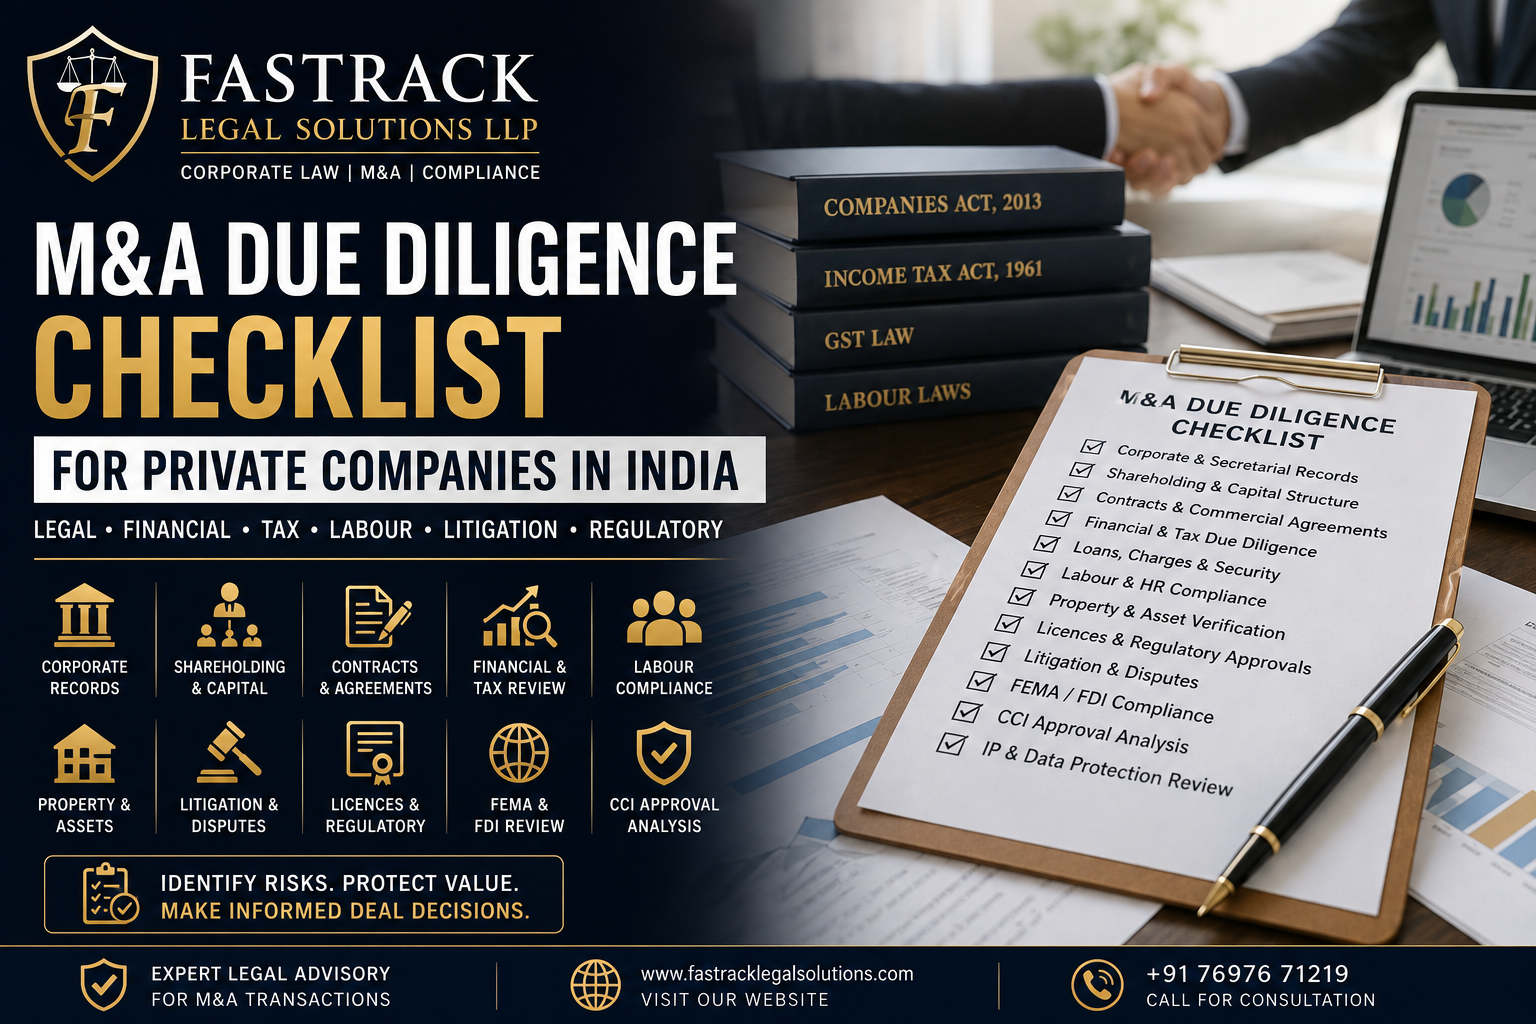
M&A due diligence is the legal and commercial process through which a buyer, investor, lender or strategic partner verifies a target company before signing or closing a transaction. A high-quality M&A legal due diligence exercise should identify not only obvious legal defects, but also liabilities, consent requirements, control gaps, regulatory exposure, employment issues, litigation risk, data vulnerabilities, tax concerns, property defects and transaction conditions that can affect valuation or deal structure.
This checklist is designed for private-company acquisitions, strategic investments, share purchases, business transfers, mergers, joint ventures and similar transactions in India.
Phase 1 — Corporate Constitution and Ownership
The first task is to verify that the target legally exists, its share capital is correctly recorded, and the proposed sellers have authority and title to transfer the transaction interest.
- Certificate of incorporation and corporate identification details.
- Memorandum and Articles of Association.
- Historical amendments to constitutional documents.
- Current and historical shareholding pattern.
- Register of members and share certificates.
- Share transfer records.
- Capitalisation table including options, warrants or convertible instruments.
- Beneficial ownership and significant beneficial ownership records.
- Shareholder agreements and investor rights agreements.
- Restrictions on transfer, pre-emption, tag, drag or ROFR rights.
- Board and shareholder approvals affecting capital.
- Subsidiary, affiliate and joint-venture structure.
Red flags: undocumented allotments, inconsistent cap table, missing share certificates, disputed ownership, nominee holdings, unrecorded beneficial ownership or third-party transfer restrictions.
Phase 2 — Corporate Governance and Authority
- Board composition and director appointments.
- Board minutes and shareholder minutes.
- Delegation of authority matrix.
- Committee approvals.
- Related-party approvals.
- Key management authorisations.
- Corporate policies and governance framework.
- Material decisions taken without documented authority.
The diligence team should identify whether historic decisions were properly authorised and whether closing the proposed transaction requires shareholder, board, lender, contractual or regulatory consent.
Phase 3 — Statutory and Regulatory Compliance
This stage should be treated as a dedicated compliance legal due diligence workstream where the target operates in a regulated or licence-dependent business.
- Corporate filings and statutory registers.
- Sector licences and registrations.
- Factory, trade, environmental and local approvals where relevant.
- Foreign investment compliance.
- FEMA and RBI filings where applicable.
- Industry-specific permissions.
- Notices, inspections and regulatory correspondence.
- Compliance defaults and pending remediation.
- Penalties or compounding proceedings.
Key question: Does the target have every licence required to continue its present business immediately after closing?
Phase 4 — Financial and Security Documentation
- Loan agreements.
- Working-capital facilities.
- Security documents.
- Charges registered over company assets.
- Corporate and personal guarantees.
- Covenants and financial ratios.
- Events of default.
- Change-of-control clauses.
- Inter-creditor arrangements.
- Related-party loans.
- Off-balance-sheet obligations.
A buyer should determine whether the transaction itself triggers a default, mandatory repayment, lender consent or release of security.
Phase 5 — Employment and Human Resources
Workforce liabilities often become purchase-price issues. A dedicated Employment & HR Legal Due Diligence review should cover:
- Employee list and classification.
- Employment agreements.
- Consultant and contractor arrangements.
- Key employee retention risk.
- Compensation, bonus and incentive plans.
- ESOPs and other equity arrangements.
- Provident fund, gratuity, ESI and other statutory obligations.
- Leave and benefit liabilities.
- Pending employee claims.
- Termination disputes.
- Confidentiality and intellectual-property assignment clauses.
- POSH compliance and Internal Committee documentation.
- Background verification practices for sensitive roles.
Red flags: key personnel without contracts, unpaid statutory dues, contractor misclassification, high attrition in critical functions, unresolved misconduct issues or weak confidentiality controls.
Phase 6 — Material Contracts
Material agreements should be reviewed through a separate Contractual Legal Due Diligence workstream.
- Top customer contracts.
- Major supplier and vendor agreements.
- Distribution agreements.
- Franchise or agency agreements.
- Technology agreements.
- Outsourcing contracts.
- Leases.
- Government contracts.
- Strategic partnerships.
- Non-compete and exclusivity arrangements.
- Confidentiality obligations.
- Indemnities and liability limitations.
- Termination rights.
- Change-of-control restrictions.
- Assignment restrictions.
- Most-favoured-customer clauses.
For each contract, the diligence report should identify whether consent, notice, novation or amendment is required before or after closing.
Phase 7 — Litigation, Claims and Investigations
- Pending litigation.
- Arbitration proceedings.
- Regulatory cases.
- Tax disputes.
- Employee disputes.
- Consumer claims.
- Criminal complaints involving the company or management.
- Government notices.
- Threatened claims.
- Internal investigations.
- Whistleblower matters.
The diligence team should estimate not only legal merits but also financial exposure, management distraction, reputational risk and potential closing conditions.
Phase 8 — Intellectual Property
- Registered trademarks.
- Trademark applications.
- Copyright ownership.
- Patent and design rights.
- Domain names.
- Software ownership.
- Employee and contractor IP assignment.
- Licensing arrangements.
- Open-source software obligations.
- Third-party infringement claims.
A business whose valuation depends on technology or brand should not be acquired without verifying chain of title to the relevant IP.
Phase 9 — Data Protection, Cybersecurity and Confidential Information
- Personal-data processing practices.
- Privacy notices and consents.
- Customer-data contracts.
- Data-processing arrangements.
- Security policies.
- Access controls.
- Cyber incidents.
- Data breaches.
- Confidential-information leakage.
- Employee access to sales and customer data.
- Retention and deletion practices.
- Cross-border transfers where relevant.
A diligence report should specifically flag whether the target possesses commercially valuable data without sufficient contractual, technical or employment safeguards.
Phase 10 — Tax and Financial Exposure
- Income-tax assessments and notices.
- GST compliance.
- Withholding-tax exposure.
- Transfer-pricing issues.
- Tax litigation.
- Deferred tax liabilities.
- Historical restructuring.
- Related-party transactions.
- Contingent liabilities.
Tax diligence should be coordinated with financial diligence so that liabilities are not duplicated or omitted from the transaction model.
Phase 11 — Related-Party and Promoter Transactions
- Loans to or from promoters.
- Related-party leases.
- Vendor relationships involving management.
- Personal assets used by the business.
- Business assets held outside the target.
- Guarantees and indemnities.
- Unrecorded promoter arrangements.
These arrangements are especially important in promoter-led businesses where operational assets, IP, property or key contracts may sit outside the acquisition vehicle.
Phase 12 — Real Estate and Property
Material owned or leased property should receive its own Property Legal Due Diligence review.
- Title documents.
- Lease deeds.
- Encumbrances.
- Mortgages.
- Land-use permissions.
- Building approvals.
- Property tax.
- Possession status.
- Litigation and acquisition risk.
- Renewal and termination terms.
If a key plant, warehouse, office or operating site has defective title or an insecure lease, the issue may be fundamental to the transaction.
Phase 13 — Insurance
- Property insurance.
- Business interruption.
- Professional indemnity.
- Directors and officers insurance.
- Cyber insurance.
- Employee policies.
- Claims history.
- Coverage exclusions.
Phase 14 — Environmental, Health and Safety
- Environmental consents.
- Waste handling.
- Pollution-control permissions.
- Hazardous-material compliance.
- Occupational safety.
- Accidents and notices.
- Remediation liabilities.
Environmental liabilities can survive ownership change and therefore require careful allocation in transaction documents.
Phase 15 — Information Requests and Management Interviews
Document review alone is not enough. The diligence team should conduct targeted management interviews where documents reveal inconsistencies, missing information or material operational dependencies.
Questions should focus on:
- Unrecorded disputes.
- Informal arrangements.
- Customer concentration.
- Key employee dependency.
- Regulatory concerns.
- Data leakage.
- Related-party arrangements.
- Expected future claims.
How to Grade Due Diligence Findings
A practical report should classify each finding rather than merely listing documents reviewed.
| Risk | Meaning | Typical Transaction Response |
|---|---|---|
| Critical | Threatens legality or viability of transaction | Stop deal, restructure or make mandatory condition precedent |
| High | Material financial or legal exposure | Price adjustment, indemnity, escrow or pre-closing remediation |
| Medium | Manageable but relevant risk | Covenant, post-closing action or specific representation |
| Low | Minor documentation or process issue | Routine remediation |
How Due Diligence Findings Should Affect Transaction Documents
A due diligence report has little value if its findings do not flow into the transaction documents. Depending on risk, findings may result in:
- Conditions precedent.
- Conditions subsequent.
- Specific indemnities.
- Representations and warranties.
- Disclosure schedules.
- Escrow or holdback.
- Purchase-price adjustment.
- Termination rights.
- Management retention.
- Insurance requirements.
- Pre-closing restructuring.
Red Flags That May Require the Buyer to Reconsider the Deal
- Unclear ownership of shares or assets.
- Material licences cannot be transferred or retained.
- Major customer contracts terminate on change of control.
- Serious undisclosed litigation.
- Fraud or integrity concerns involving management.
- Critical IP is owned by promoters or third parties.
- Large unpaid statutory liabilities.
- Material property-title defects.
- Evidence of customer or sales-data leakage.
- Financial records materially inconsistent with legal documents.
Frequently Asked Questions
What is legal due diligence in an acquisition?
It is the process of reviewing a target company’s legal rights, obligations, liabilities, contracts, compliance and disputes before an acquisition or investment.
What is a red-flag due diligence report?
A red-flag report focuses on material issues capable of affecting valuation, transaction structure, closing conditions or the buyer’s decision to proceed.
Does due diligence happen before signing or closing?
It may occur before signing, between signing and closing, or in phases. The transaction structure determines timing.
Can a buyer rely only on seller warranties?
Warranties are important but are not a substitute for diligence. Diligence can identify risks before the buyer becomes dependent on post-closing claims.
Why is change-of-control review important?
Contracts, licences or financing arrangements may require consent or permit termination when ownership changes.
Conclusion
A disciplined M&A due diligence process should answer three questions: what is the risk, how material is it, and how should the transaction respond? The strongest diligence reports connect documentary findings to valuation, closing conditions, indemnities, contractual protections and post-closing remediation.
This article is for general informational purposes and does not constitute legal advice, solicitation or advertisement. Transaction structures and diligence scope vary materially by industry, target, deal type and applicable law.